Saving or investing in Ireland: matching contractor money to its timeframe
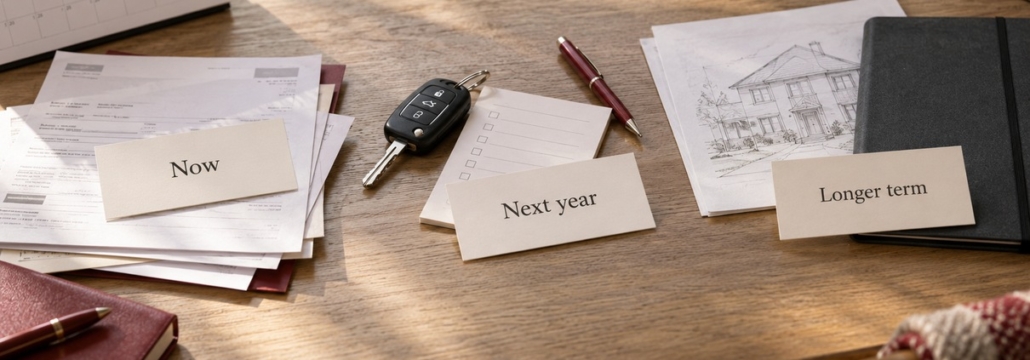
A healthy account balance does not necessarily mean you have money available to invest. For a contractor, the same balance may need to cover a quieter month, a planned purchase and a goal that is several years away.
When weighing up saving or investing in Ireland, start with the date you might need the money, not the most attractive headline return. The aim is to give each part of your money a clear purpose, then consider the access, risk and costs that suit it.
These five checks will help you prepare for a discussion with your financial adviser. They concern personal financial planning, not a recommendation about investing company funds.
1. Give each goal a date
Write down what you are setting money aside for and the earliest date you could need it. Be specific: “Replacing the car next spring” tells you more than “Growing my savings”.
Separate known commitments from money that genuinely has a longer timeframe. A contractor might have:
- Money for essential costs if the next assignment starts late.
- Savings for a purchase with an agreed deadline.
- A longer-term personal goal whose spending date is flexible.
An investment might be saleable, but that does not mean its value will be suitable when a bill falls due. A goal with a fixed date needs a different discussion from one you can postpone.
If you operate through a limited company, do not treat the company’s account balance as your personal surplus. Ask your accountant to confirm ownership, liabilities and what can appropriately become personal money before making a personal investment plan.
For a deeper look at the reserve itself, use our guide to planning an emergency fund when your income varies.
2. Check access before comparing rates
Savings accounts are not all equally accessible. The CCPC’s savings guidance distinguishes accounts that permit withdrawals on demand, those requiring notice and those with a fixed term. Read the conditions rather than relying on the word “savings”.
Before moving money, ask:
- How quickly can I withdraw it?
- Is there a notice period or withdrawal restriction?
- Could early access involve a penalty or lost interest?
- Is the rate fixed, variable or conditional?
Deposit protection is a separate check. The Central Bank explains that the Irish Deposit Guarantee Scheme covers eligible deposits up to €100,000 per person, per institution. Deposits with institutions authorised in another EU country fall under that country’s scheme. Confirm the institution and applicable scheme rather than assuming every account has Irish protection.
An investment is not equivalent to a protected deposit. The Central Bank’s Investor Compensation Scheme explanation makes clear that it does not compensate for poor market performance. Ask what protections apply to the particular product, and what they do not cover.
3. Decide what risk the goal can carry
Your comfort with uncertainty matters, but so does what a loss would do to the goal. Would a fall in value delay a home purchase, reduce money for essential bills or simply affect a flexible longer-term ambition?
The CCPC’s investment guidance explains that products differ in risk and access. Spreading investments across assets can reduce reliance on one holding, but diversification does not remove the possibility of loss.
A longer timeframe is not a guarantee that an investment will recover before you need it. Discuss both your willingness to accept fluctuations and your financial ability to absorb a loss.
Remember the spending-power question
Cash also has a longer-term consideration. If prices rise faster than savings grow, the money can buy less even while the account balance increases. The CCPC’s inflation guidance explains this distinction.
That is a reason to review longer-term money, not a reason to invest funds needed for an invoice gap or imminent expense. Protecting access and considering future purchasing power are different objectives.
4. Compare costs and tax questions
Two products with similar descriptions can have different costs. The CCPC explains that charges and tax can reduce the return you retain, and that tax treatment depends on how the investment is structured.
Ask for the relevant documents and a clear explanation of:
- Any charge taken from the money you contribute.
- Ongoing fund, account, platform or advice charges.
- Costs of withdrawing, transferring or switching.
- Applicable taxes and any reporting you must arrange.
Avoid comparing a savings rate with an investment illustration as though both were promised outcomes. Check what is guaranteed, what is only illustrative and whether the figures account for costs.
This guide deliberately does not quote product rates or tax calculations. Ask your adviser and, where appropriate, your tax professional to explain the current position for the actual arrangement you are considering.
5. Review the plan when your contract changes
A plan that worked during a long assignment may need attention when the contract ends or family commitments increase. The CCPC recommends reviewing investments at least annually and sooner when circumstances change.
For a contractor, bring the review forward if payment timing changes, your accessible reserve falls or a spending goal moves closer. Revisit contributions, access and the risk you can carry. A review is not an instruction to sell: switching or withdrawing can create charges and tax consequences.
A practical contractor example
Imagine a contractor who has a contract ending soon, a car purchase planned next year and a separate goal without a firm spending date. This is an illustration, not a recommended allocation.
Putting the whole balance into one product would ignore those different deadlines. Instead, the contractor can record the amount and access needed for each purpose, then discuss whether any remaining personal money is suitable for investment. If the next contract is delayed, that assessment changes. The useful starting point is the household plan, not a universal percentage.
Your savings and investment review checklist
Before your appointment:
- List each goal and the earliest date you could need its money.
- Identify money already committed to bills, reserves or planned spending.
- Gather current account terms and investment statements.
- Write down the impact a fall in value would have on each goal.
- Ask about access, charges, protection and tax responsibilities.
- Agree when changes in income or circumstances should trigger a review.
The CCPC Investment Readiness Tool offers an additional self-assessment. It is a starting point for reflection, not personal advice or an endorsement of a product.
Build the plan around your contracting life
C Plus Financial works with professional contractors on savings, investments and wider financial planning. Its savings and investment service connects your goals with discussions about timeframe, access and risk.
Book a consultation to discuss your circumstances with an adviser and identify the questions that need to be answered before choosing a product.
Important information
This article provides general information only and does not constitute personal financial, investment or tax advice. Product suitability, tax treatment and entitlements depend on individual circumstances and may change. Speak to an appropriately qualified adviser before taking action.
The value of investments can fall as well as rise.
Sources
- CCPC, The difference between saving and investing.
- CCPC, Choosing the right savings option.
- CCPC, Types of investment.
- CCPC, The impact of inflation.
- CCPC, Taxes and charges.
- CCPC, Reviewing your investments.
- CCPC, Investment Readiness Tool.
- Central Bank of Ireland, Deposit Guarantee Scheme.
- Central Bank of Ireland, Compensation schemes for consumers of authorised firms.
Sources accessed and guidance checked 9 October 2026. Prepared by the C Plus Financial editorial team. Adviser review pending.